8 min read
What Is Loan-to-Value?
Loan-to-value, or LTV, measures how much you owe compared with the current value of the assets securing your loan. Borrow $50,000 against $100,000 of crypto and your starting LTV is 50%. If that collateral falls to $80,000, the same debt becomes a 62.5% LTV.
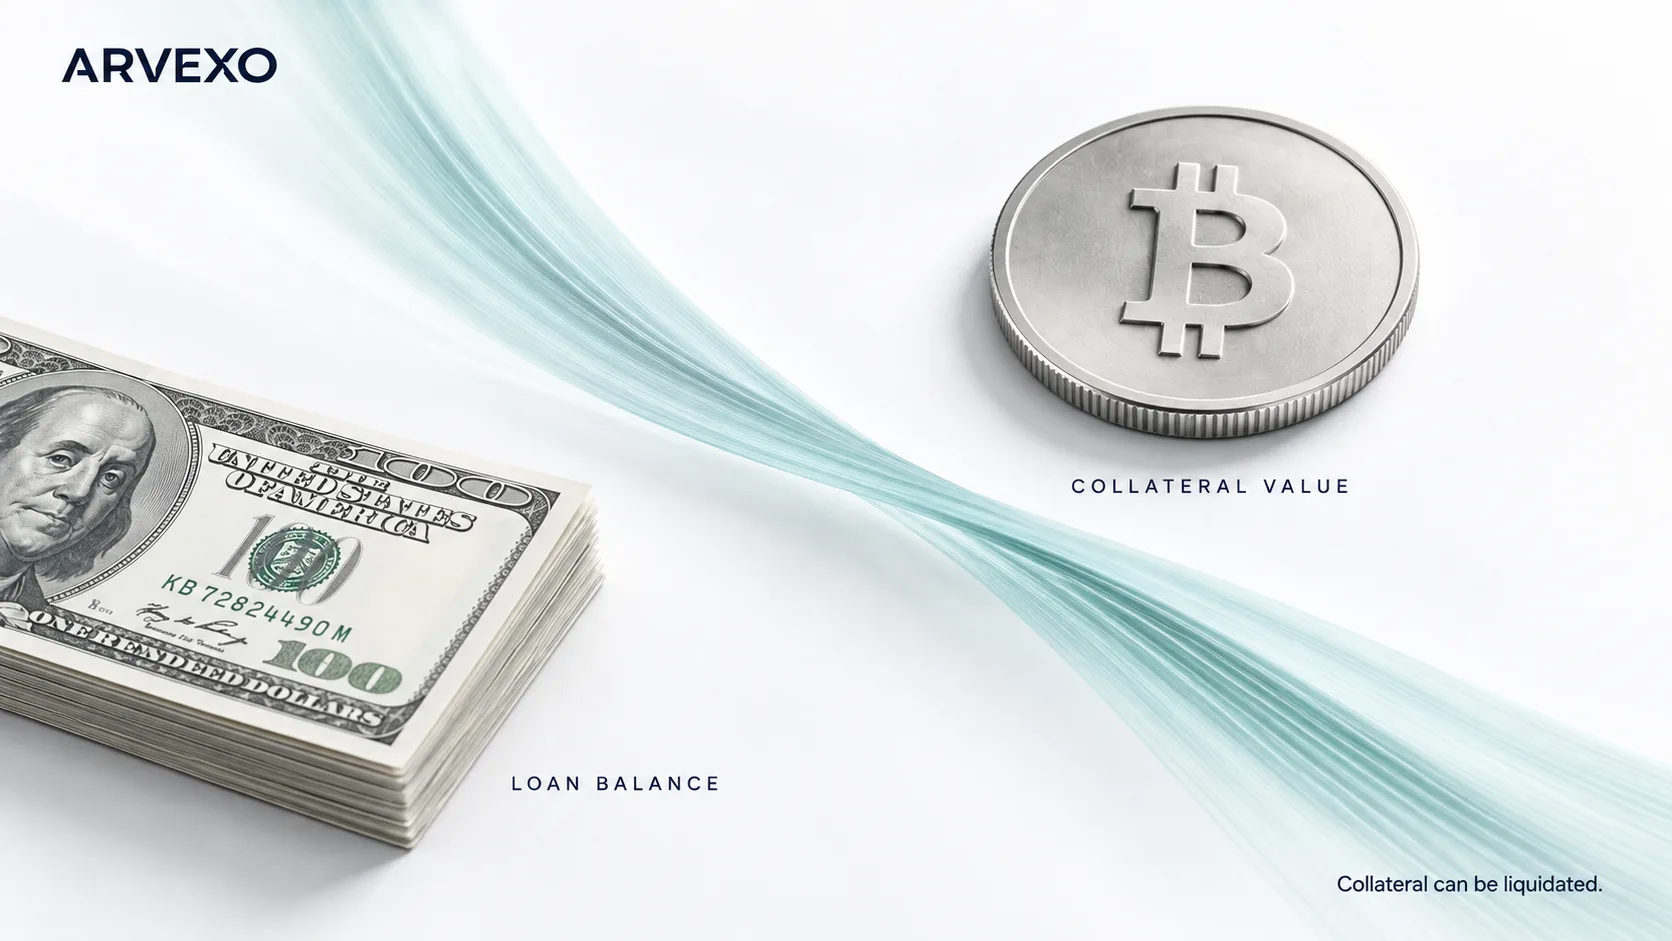
That moving ratio affects how much you can borrow, when you may need to add collateral and when a lender may sell it. Understanding the calculation is more useful than treating the maximum available loan as a target.
The LTV formula
LTV = outstanding loan balance ÷ collateral value × 100 $50,000 ÷ $100,000 × 100 = 50% LTV
The Business Development Bank of Canada defines LTV as the relationship between a loan and its collateral value. For crypto, that value can move quickly. Use the collateral pledged to the loan, not your entire wallet or the amount you originally paid for the asset.
The examples below use a USD loan, one collateral asset and hypothetical Bitcoin prices. Unless stated otherwise, the balance excludes additional interest and fees, and the collateral quantity stays unchanged. They explain the arithmetic, not a personalised borrowing recommendation.
Case 1 / Set your starting LTV
Case 1: choose how much collateral to commit
Suppose you want a $50,000 principal balance and Bitcoin is worth a hypothetical $100,000 per coin. To find the collateral required, divide the loan by your chosen starting LTV, written as a decimal.
Required collateral value = loan amount ÷ starting LTV
At 50% LTV, $50,000 ÷ 0.50 = $100,000 of collateral, or 1 BTC. At 30%, the same loan needs approximately $166,666.67 of collateral.
| Starting LTV | Collateral value for a $50,000 loan | BTC at $100,000 per coin |
|---|---|---|
| 30% | $166,666.67 | About 1.6667 BTC |
| 50% | $100,000.00 | 1 BTC |
| 70% | $71,428.57 | About 0.7143 BTC |
The lower ratio ties up more collateral for the same amount of borrowing. Alternatively, if you have a fixed $100,000 of collateral, choosing 30% rather than 50% LTV reduces the principal from $50,000 to $30,000.
Maximum starting LTV is a limit, not a safety rating
The maximum starting LTV is the highest ratio a lender permits when a loan begins. It is different from the margin-call or liquidation threshold during the loan.
Arvexo's public collateral parameters, checked on 21 September 2026, listed a 70% maximum starting LTV for BTC. Other assets had different limits. The 70% row above illustrates that published setting; it is not a promise of availability or a recommendation to borrow at the limit. Confirm the actual asset parameters in your quote and agreement.
A lower LTV gives more room for a price fall, but also places more assets into the custody arrangement for the same loan. Consider both the price buffer and the amount of collateral committed.
Use the debt balance, not the cash received
Arvexo's public terms state that its origination fee is deducted from principal. At an illustrative 1% fee, a $50,000 principal delivers $49,500 before other charges. The opening LTV against $100,000 of collateral is still 50%, not 49.5%. Fees withheld from the payout do not reduce the debt owed.
Case 2 / When prices fall
Case 2: a price fall pushes LTV up
Start with a $50,000 balance secured by 1 BTC worth $100,000. A price fall changes the denominator of the formula, even if you have made every payment on time.
| Hypothetical BTC price | Loan balance | Resulting LTV |
|---|---|---|
| $100,000 | $50,000 | 50% |
| $80,000 | $50,000 | 62.5% |
| $70,000 | $50,000 | About 71.43% |
| $62,500 | $50,000 | 80% |
| About $58,824 | $50,000 | About 85% |
A 20% fall in collateral value takes LTV from 50% to 62.5%. It does not add 20 percentage points to the ratio. Calculate the new value each time rather than adding the price move to the old LTV.
Work out the distance to a threshold
Arvexo's public BTC quote, checked on 21 September 2026, showed an 80% margin-call threshold and an 85% liquidation threshold. These are the assumptions used here; your agreement specifies the applicable thresholds and response requirements.
With an unchanged balance and collateral quantity, the percentage price fall to a threshold is:
Price fall = (1 − starting LTV ÷ threshold LTV) × 100%
For a 50% starting LTV and an 80% margin-call threshold, (1 − 50 ÷ 80) × 100% = 37.5%. Starting at 70% instead leaves a 12.5% fall before the same threshold. Starting at 30% leaves 62.5%. These are mathematical distances, not forecasts or guarantees.
A margin call requires action; liquidation can mean a collateral sale. In its analysis of crypto lending, the European Central Bank describes how declining collateral values can lead to margin calls and defaults. Fast price changes can leave little time to respond, so an alert should not be treated as a guaranteed grace period.
The ratio can also rise if interest or fees are added to the outstanding balance, or if collateral is withdrawn. Check exactly what the lender includes in each side of its calculation.
Case 3 / Restore your target
Case 3: bring LTV back to a chosen level
After the fall to $80,000 per BTC, the $50,000 loan has a 62.5% LTV. Suppose you want to return to 50%. This is an illustrative target, not necessarily the level required to resolve a margin call under your agreement.
Option A: add collateral
Keep the balance at $50,000. At a 50% target, you need $50,000 ÷ 0.50 = $100,000 of collateral. You currently have $80,000, so add $20,000 of collateral, equivalent to 0.25 BTC at that hypothetical price.
Once credited, 1.25 BTC × $80,000 = $100,000. Your LTV is $50,000 ÷ $100,000 = 50%. This improves the ratio without reducing the debt or, by itself, the interest charged on that debt.
Option B: repay principal using money outside the collateral
Keep collateral at $80,000. A 50% target permits a $40,000 balance, so reduce principal by $10,000. The new LTV is $40,000 ÷ $80,000 = 50%.
Arvexo's repayment guidance says partial repayments reduce principal and subsequent interest. Check payment allocation and any applicable fees: the example assumes the full $10,000 reduces principal.
| Action at an $80,000 BTC price | New balance | Collateral value | LTV |
|---|---|---|---|
| Add $20,000 of collateral | $50,000 | $100,000 | 50% |
| Repay $10,000 from outside funds | $40,000 | $80,000 | 50% |
Selling pledged collateral changes both sides
Selling $10,000 of the pledged BTC and applying all proceeds to principal is a different calculation. Debt falls to $40,000, but collateral falls to $70,000. LTV becomes about 57.14%, not 50%.
Ignoring costs, reaching 50% this way would require a $20,000 collateral sale: $30,000 debt ÷ $60,000 collateral = 50%. This is arithmetic only; it does not mean you can withdraw or sell pledged assets freely. Any sale or release must follow the lender's process, and costs or taxes may change the result.
Adding collateral also depends on transfer confirmation and crediting. A transfer in progress does not necessarily improve your live LTV. Prices may move before a deposit or repayment takes effect.
Manage the loan, not just the ratio
Choose an LTV you can manage when prices move
There is no single LTV that makes every crypto-backed loan safe. A lower starting ratio widens the price buffer, while your ability to repay, access additional funds and respond promptly determines what you can do if the buffer shrinks.
Does paying interest lower LTV?
No. On an interest-only loan, paying the interest due does not reduce principal. With collateral value unchanged, principal-based LTV stays the same.
Does a higher crypto price let me withdraw collateral?
A higher price generally lowers LTV when the balance and asset quantity stay fixed. It does not automatically make collateral available to withdraw. Removing collateral raises LTV again, and any release depends on the lender's rules and approval process.
What should I check before borrowing?
- The starting LTV, warning level, margin-call level and liquidation level.
- The price source and any interest or fees included in the balance.
- The principal amount, usable cash after fees and final repayment plan.
- What a substantial price fall would do to the ratio.
- How much external cash or additional collateral you could actually access.
- How deposits and repayments are credited, including any delays or charges.
Is a 67% LTV good?
It is close to Arvexo's 70% maximum for Bitcoin. At 67%, a margin call (80%) arrives after a 16.3% price fall and liquidation (85%) after 21.2%. That is less than a bad week in several past drawdowns. A 50% starting LTV gives 37.5% and 41.2% respectively. "Good" depends on whether you could fund a top-up at those prices.
Use the Arvexo calculator for an indicative estimate, then check the actual agreement. For the next step, read Margin calls and liquidation. Choose the loan around your repayment plan and ability to respond, rather than the highest amount displayed.
Collateral can fall in value and be sold. This article is for general informational purposes only and does not constitute financial, investment, legal, or tax advice.
Sources
- Business Development Bank of Canada, definition of loan-to-value as the relationship between a loan and its collateral value.
- European Central Bank, analysis of crypto lending, on how declining collateral values can lead to margin calls and defaults.
- Arvexo public collateral parameters and BTC quote, checked on 21 September 2026.